
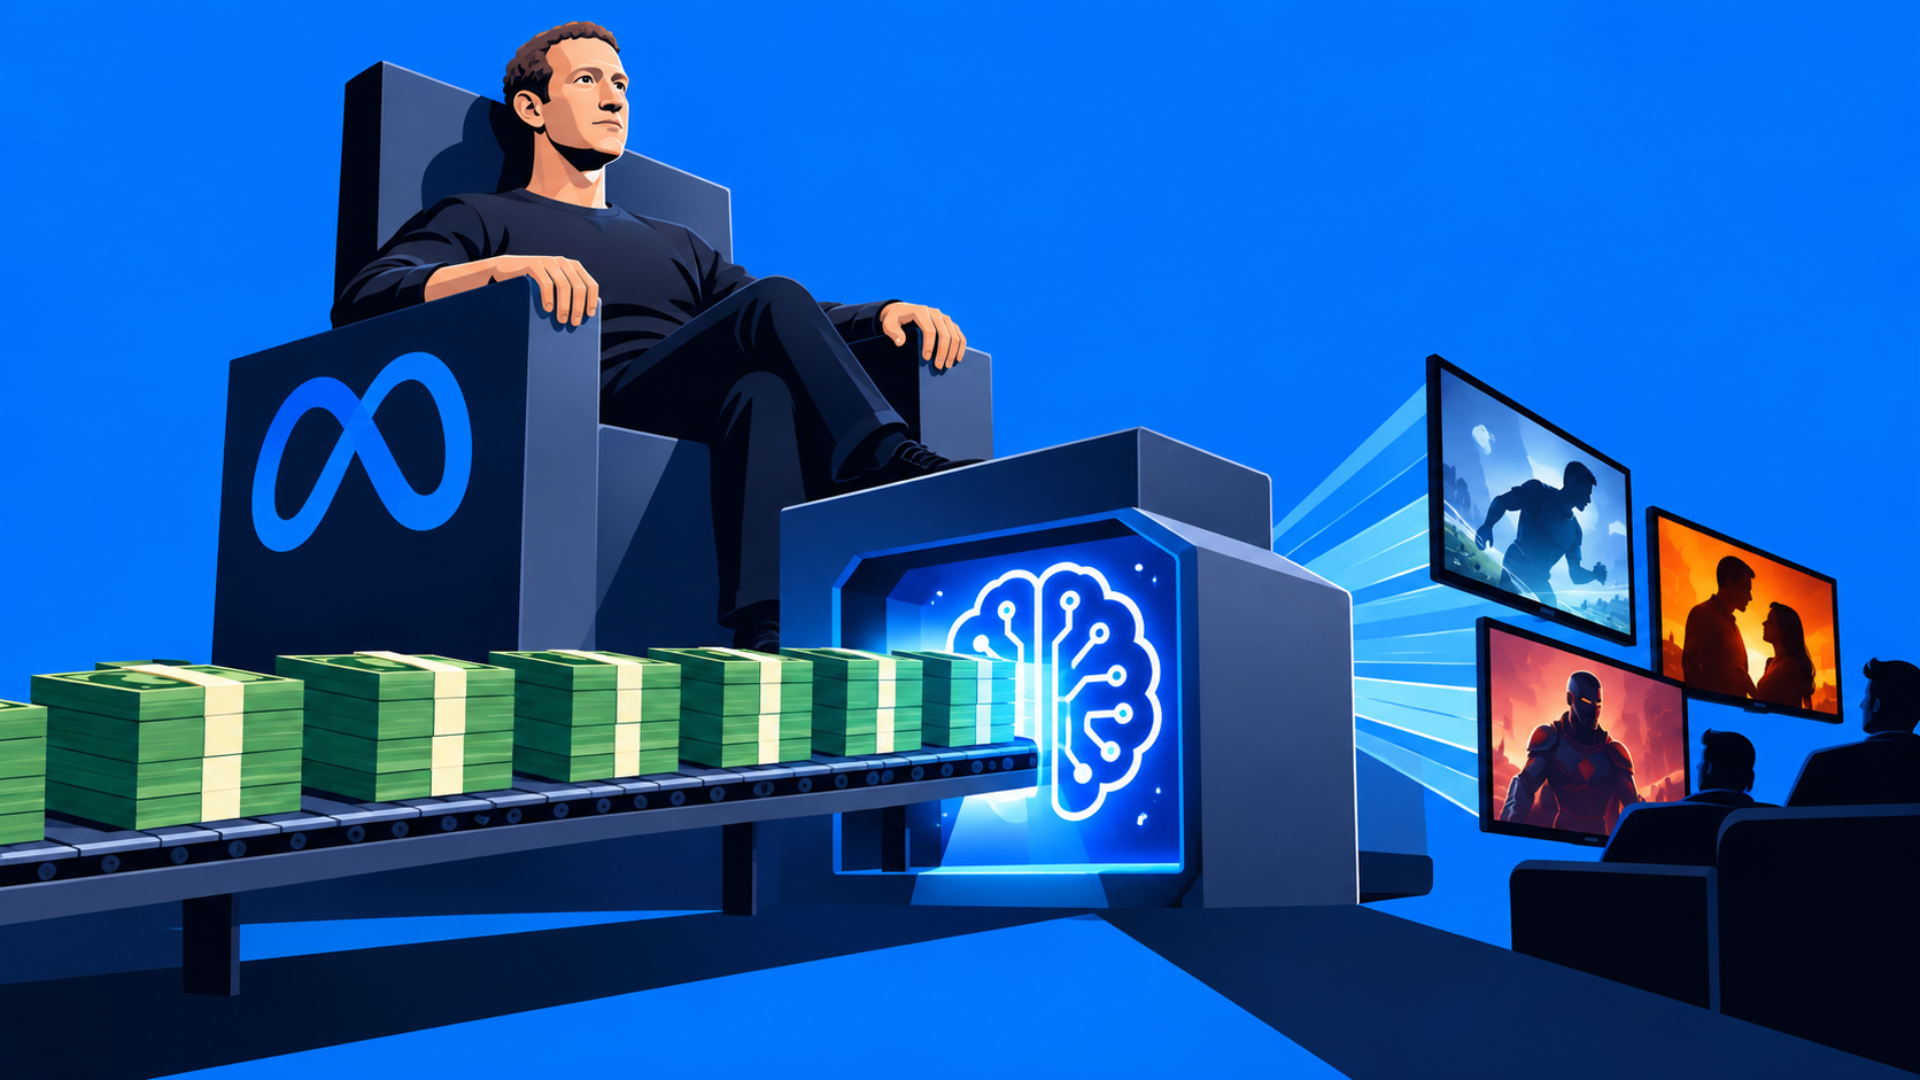
Meta is creating a publicly traded class of nonvoting stock that it can use to finance its AI expansion without weakening Mark Zuckerberg’s control. The company spent more on capital projects than it generated in operating cash during the third quarter, while its share repurchases have stopped and infrastructure commitments continue to grow.
The new Class C shares will let Meta raise equity, compensate employees and finance acquisitions without issuing additional votes. Future issuances could dilute existing shareholders’ economic interests while leaving Zuckerberg’s majority voting position intact.
Meta’s Capital Spending Exceeds Operating Cash as Buybacks Stop, Increasing Pressure to Raise Equity
Meta spent $34.91 billion on capital expenditures, including finance lease principal payments, during the third quarter. It generated $32.79 billion in operating cash flow, producing negative free cash flow of $2.12 billion compared with positive $10.63 billion a year earlier.
The company now expects 2026 capital spending of $135 billion to $145 billion, raising the bottom of its previous forecast by $5 billion.
Meta’s advertising business continues to grow. Third-quarter advertising revenue reached $63.06 billion, up from $50.08 billion a year earlier. Ad impressions increased 10%, while the average price per ad rose 14%.
But rising advertising revenue hasn’t stopped the company from changing how it allocates capital.
Meta repurchased no Class A shares during the first nine months of 2026. During the same period in 2025, it spent $26.25 billion buying back stock.
That reversal is significant. Repurchases reduce the shares outstanding and increase continuing investors’ proportional ownership. Future equity sales would move Meta in the opposite direction, spreading its earnings across a larger shareholder base.
The company still held $82.45 billion in cash, cash equivalents and marketable securities at the end of September. Its immediate liquidity position remains substantial, but AI infrastructure is absorbing capital at a pace that makes additional financing options increasingly attractive.
Meta Can Issue Class C to Finance AI Without New Votes, Leaving Shareholders Exposed to Dilution
Meta plans to distribute one Class C share for every outstanding Class A or Class B share after its amended corporate charter takes effect on January 19, 2027.
The company expects its Class A share price to adjust as it would following a two-for-one stock split. The initial distribution won’t raise capital, change shareholder voting power or dilute existing investors’ proportional economic ownership.
Future issuances provide the financing flexibility.
Meta can sell newly issued Class C shares to investors, compensate researchers and engineers with stock, or use shares to acquire companies. The recipients receive an economic interest in Meta without gaining the voting rights attached to its existing Class A and Class B shares.
Issuing stock instead of borrowing also avoids the repayment obligations associated with additional debt. The cost appears in shareholders’ proportional claims on future earnings.
If Meta issues more Class C shares, its existing investors will own a smaller percentage of the combined equity unless they acquire additional stock. Zuckerberg’s percentage of the company’s votes can remain unchanged.
The market will also determine what that flexibility costs. Nonvoting Class C shares could trade at a discount to voting Class A shares, forcing Meta to issue more stock to raise the same amount of capital. The board designed the initial distribution to establish a liquid market for Class C and minimize that potential discount.
Zuck Gains a Phased Liquidity Path While Class C Investors Receive No New Voting Power
Zuckerberg controlled approximately 60.6% of Meta’s voting power as of October 1, 2026. The company’s independent special committee acknowledged that he wasn’t facing an imminent loss of majority control.
Future equity financing and personal share sales could gradually reduce that majority. The new structure addresses both.
Zuckerberg will receive Class C shares through the same initial distribution as other shareholders. Under the Founder Alignment Agreement, he can freely sell 20% of those shares without a corresponding reduction in his voting power.
Most of the remaining 80% initially carry restrictions. Selling those shares generally requires corresponding sales or conversions of voting stock unless the restrictions have been released.
The agreement provides for the restrictions to be lifted on another 2.5% of his initial Class C allocation for each qualifying quarter in which he continues serving in a full-time leadership role. After 32 qualifying quarters, the initial allocation can become fully unrestricted.
Those terms give Zuckerberg a path to reduce his personal economic exposure over time without a proportional reduction in voting control. The independent directors negotiated continued-service conditions and other commitments around that arrangement.
Existing Class A shareholders retain their voting rights. Investors who purchase newly issued Class C stock will participate in Meta’s financial performance without receiving corresponding influence over its spending priorities, acquisitions or leadership.
Meta’s AI Improves Reels Engagement and Ad Conversions, Raising the Performance Bar for Streaming Competitors
Meta’s AI investments are already producing measurable improvements inside the advertising business funding much of the expansion.
During the third quarter, changes to Instagram’s recommendation systems increased Reels time spent by more than 4%. The company’s expanded GEM advertising ranking model generated a 1.7% increase in conversions for offsite conversion campaigns and a 9.6% increase in app ad conversions.
Meta’s creator partnership advertising business also grew more than 97% year over year, surpassing a $15 billion annual revenue run rate.
Those results connect Meta’s infrastructure spending directly to the competition for video attention and advertising budgets. Better recommendations increase engagement and advertising opportunities. More effective targeting and creative tools can improve advertiser returns, making additional spending on Meta’s services easier to justify.
Meta is also restricting TikTok’s ability to advertise across Facebook and Instagram, limiting a direct video competitor’s ability to purchase audience growth through Meta’s services.
The company is financing a broader AI business that includes Muse, enterprise software and potential transaction revenue. Its established advertising operation provides revenue today while those newer products develop.
Class C gives Meta the option to sustain investment in both areas even when capital spending consumes more cash than operations generate.
That flexibility strengthens its competitive position against companies depending on advertising growth to support programming, distribution and technology costs.
The Streaming Wars Take
Ad-supported streaming services face a more demanding standard for demonstrating advertising performance as Meta improves its recommendation, targeting and creative systems.
Incremental reach beyond social feeds, household-level frequency control, conversion measurement and attribution become more valuable when advertisers can compare streaming campaigns with increasingly automated social advertising products.
Meta’s additional equity financing option could help it continue developing those capabilities through periods of negative free cash flow. Streaming competitors will encounter the effects in campaign performance, advertising budgets and competition for technical talent.
For Meta shareholders, future Class C issuance introduces another financial test. If nonvoting shares trade at a discount to Class A stock, raising capital will require issuing more shares, increasing the dilution associated with AI expansion.
Zuckerberg retains the voting power to direct the investments. The market determines how much economic ownership Meta must sell to finance them.
The cost of preserving control will ultimately be measured in the share of future earnings Meta must give up to keep funding its AI ambitions.
The Streaming Wars is intentionally ad-free
We don’t run display ads. Not because we can’t, but because we don’t believe in them.
They interrupt the reading experience. They cheapen the work. And they burn advertisers’ money on impressions nobody actually wants.
So we chose a different model.
We say the things people in this industry are already thinking but don’t say out loud. We connect the dots beyond the headline and focus on explaining why things matter to the people working in this business.
If you believe industry coverage can exist without clutter and interruption, you can support it here → SUPPORT TSW.
Support is optional. But it directly funds research and continued coverage — and helps prove this model can work.
Support TSW →